

As of the report’s release, cumulative module capacity under the Approved List of Models and Manufacturers (ALMM) List-I stood at 225.5 GW, while cumulative cell capacity under ALMM List-II stood at nearly 35.5 GW.
“Domestic cell shortages have become the biggest near-term challenge for India’s solar market. Module capacity has expanded rapidly, but cell supply has not kept pace, tightening availability and pushing up prices for compliant modules and sharply slowing project activity. Many module manufacturers are struggling to maintain production because of limited domestic cell availability. Installed cell capacity overstates actual availability, as new lines take months to reach stable commercial production. ALMM List-II has intensified the pressure by increasing dependence on domestic cell supply before enough capacity was commercially available,” commented Raj Prabhu, CEO at Mercom Capital Group.
As of June 2026, cumulative module manufacturing capacity in India was 261.7 GW, and cell capacity 36.6 GW.
The top 10 manufacturers accounted for 60% of module manufacturing capacity.
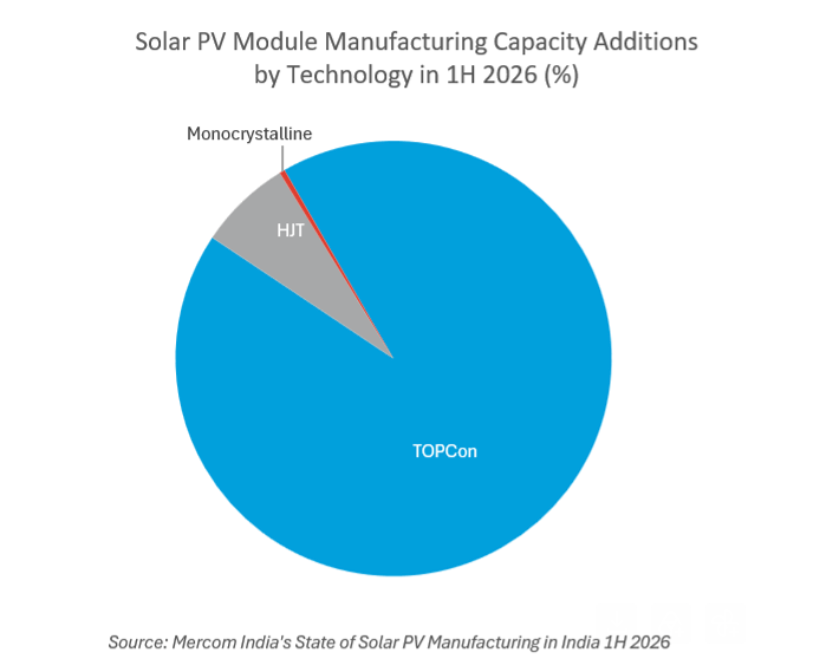
Tunnel Oxide Passivated Contact (TOPCon) accounted for the largest share of ALMM-listed module manufacturing capacity at 80% as of June 2026, followed by monocrystalline PERC/TOPCon at 11% and Mono PERC at 4%. HJT accounted for 3%, while thin-film technology represented 2% of the total ALMM-listed capacity.
“Until commercially available cell supply catches up with demand, the entire industry will remain under pressure, with manufacturers facing production constraints and developers facing commissioning delays,” added Prabhu.
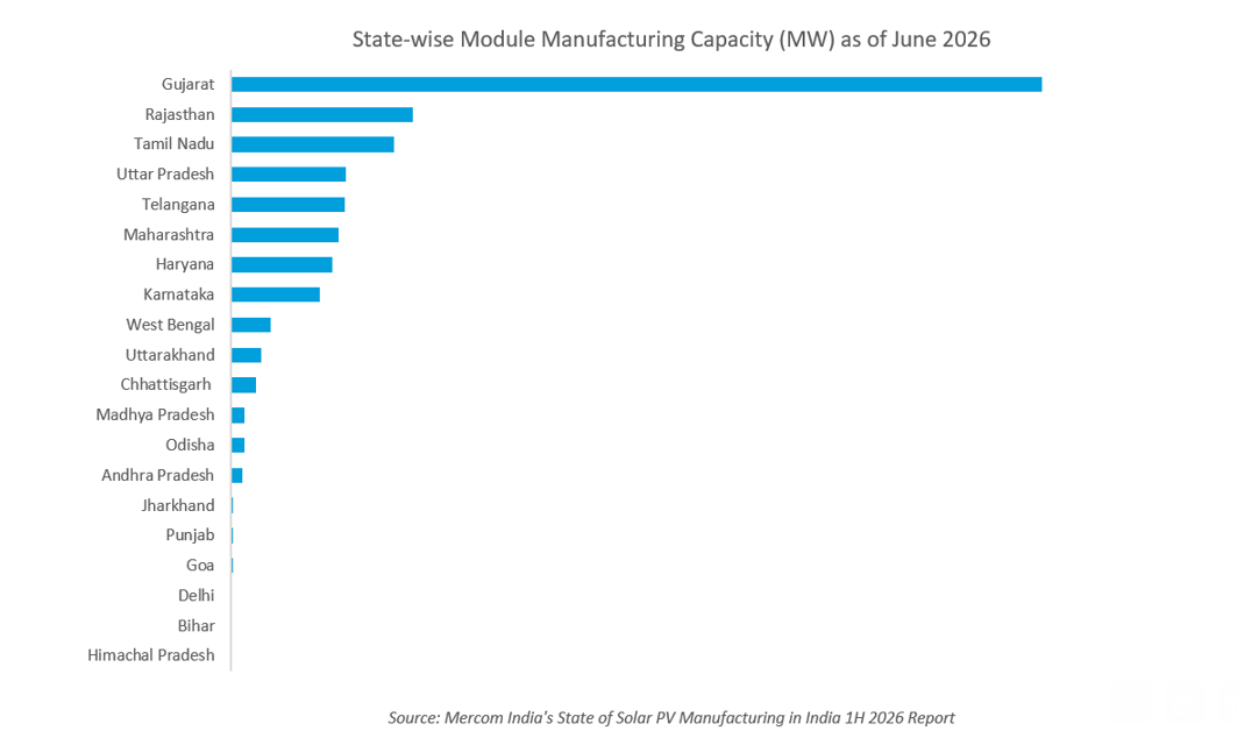
Gujarat remained the most favorable destination for solar module manufacturing production, accounting for nearly 45% of capacity as of June 2026. Rajasthan and Tamil Nadu followed with module production capacities of 26.1 GW and 23.4 GW.
Gujarat also held the largest annual solar cell production capacity at 37%. Tamil Nadu and Telangana were other top states, with capacities of 4.3 GW and 4.2 GW, respectively.
In 1H 2026, India’s imports of solar cells and modules increased 18% compared to 1H 2025. Cells accounted for 81% of total imports, while modules accounted for 19%.
The U.S. remained India’s largest solar export destination in 1H 2026, accounting for 92% of total exports.
Key Highlights from the Report:
-
India added 50.6 GW of solar module and 9.7 GW of cell capacity in 1H 2026
-
The top three states for module manufacturing were Gujarat, Rajasthan, and Tamil Nadu
-
Gujarat, Tamil Nadu, and Telangana were the leading states for solar cell manufacturing
-
In 1H 2026, India’s imports of solar cells and modules increased 18% from 1H 2025.
-
The top 10 manufacturers accounted for 60% of the country’s module manufacturing capacity