

Highlights:
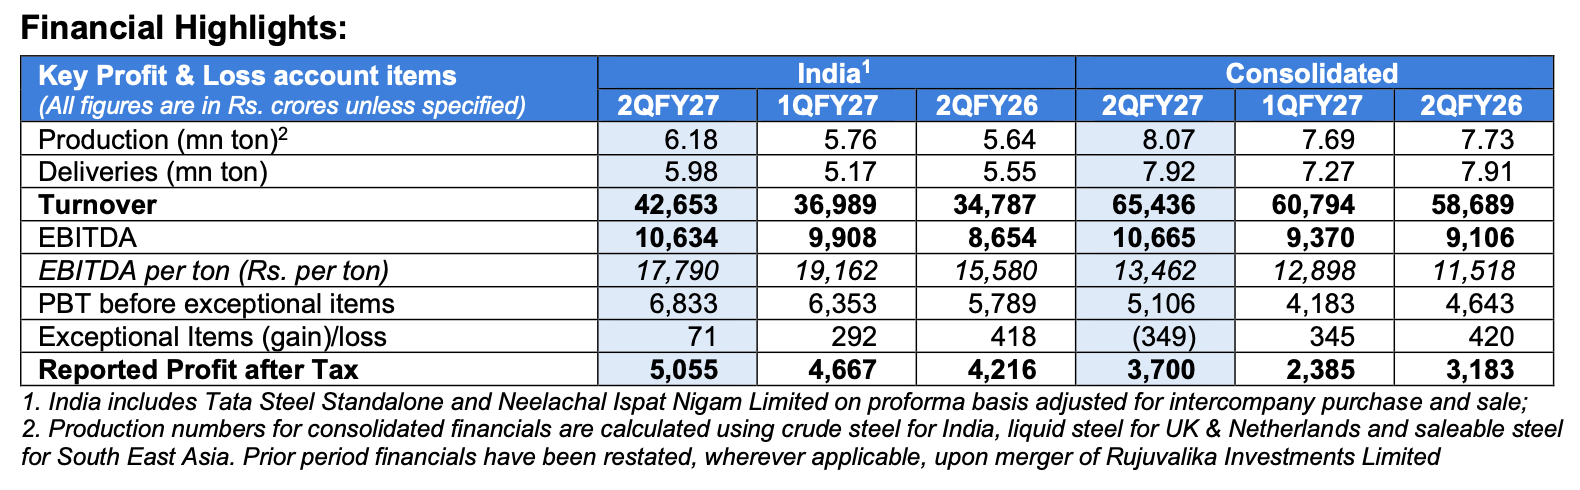
▪ Consolidated Revenues for the Jul – Sep 2026 quarter were Rs 65,436 crores and EBITDA was Rs 10,665 crores with a margin of around 16%. EBITDA improved by 14% QoQ and 17% YoY.
o India1 revenues were Rs 42,653 crores and EBITDA was Rs 10,634 crores, which translates to a margin of 25%. Crude steel production was up 7% QoQ to 6.18 million tons. Deliveries were up 16% QoQ to 5.98 million tons.
o Netherlands revenues were €1,395 million and EBITDA was €72 million, aided by the restart of the Direct Sheet Plant in early August. Liquid steel production was 1.52 mn tons and deliveries were 1.30 mn tons.
o UK revenues were £411 million and EBITDA loss stood at £56 million. Deliveries stood at 0.38 million tons in the quarter.
▪ Consolidated Revenues for the half year were Rs 1,26,231 crores and EBITDA was Rs 20,035 crores with a margin of around 16%. EBITDA improved by 21% YoY despite the challenging operating environment.
o India1 revenues were Rs 79,641 crores and EBITDA was Rs 20,541 crores, which translates to an EBITDA margin of 26%. EBITDA improved by 27% YoY.
o Netherlands revenues were €2,840 million and EBITDA was €76 million.
o UK revenues were £895 million and EBITDA loss narrowed by 22% YoY to £83 million.
▪ The company spent around Rs 3,280 crores on capital expenditure during the quarter and Rs 6,860 crores for the half year.
o Significant capex projects underway include 4.8 MTPA capacity expansion at Neelachal Ispat Nigam Limited and downstream growth projects such as the 0.7 MTPA Hot Rolled Pickling & Galvanising Line and 300 kt of the Tinplate expansion.
▪ Net debt stood at Rs 91,423 crores and Net debt to EBITDA was 2.4x. Our group liquidity remains strong at Rs 40,076 crores, which includes cash & cash equivalents of ~Rs 10,300 crores.
T V Narendran, Chief Executive Officer & Managing Director, said, “We delivered strong growth in deliveries and earnings this quarter, backed by a resilient supply chain and close customer engagement, despite ongoing geoeconomic uncertainty and higher raw material costs. Deliveries grew 9% QoQ to ~7.92 million tons and EBITDA was up 14% QoQ to ~Rs 10,665 crores. India continued to be the cornerstone of our performance with volumes growing 16% QoQ despite a seasonally softer quarter, reflecting the strength of our market presence and customer reach. Our Automotive & Special Products vertical achieved ‘best ever’ 2Q volumes of ~1.1 million tons, driven by 26% growth in hi-end sales. Tata Tiscon sales reached ~2.7 million tons over the last twelve months and generated revenues ~$1.8 billion. Our e-commerce platforms, Aashiyana and DigECA, generated Gross Merchandise Value of around Rs 2,961 crores, up 50% YoY. Downstream sales maintained their growth momentum, along with significant gains in Tata Steel colors and Tinplate. We also expanded presence in emerging segments such as shipbuilding, data centers and containers. We continue to make steady progress on our volume and value growth agenda in India. The 4.8 MTPA expansion at Neelachal Ispat Nigam Limited has entered the execution phase. Construction is progressing on the Hot Rolled Pickling & Galvanising Line and the Tinplate expansion project. In Netherlands, the successful restart of the Direct Sheet Plant and its return to rated capacity has supported improvements in both the product mix and cost profile. In the UK, while the Llanwern pickle line is now fully operational, the market conditions continue to be influenced by elevated imports and inventory build-up across parts of the value chain. We remain engaged with policymakers and regulators to support a more balanced and sustainable market environment.”