

Q2 FY27 was a strong quarter. The Company’s core business combined continued growth momentum with margin expansion, while it invested aggressively in InstaHelp, where unit economics improved even as the business scaled rapidly.
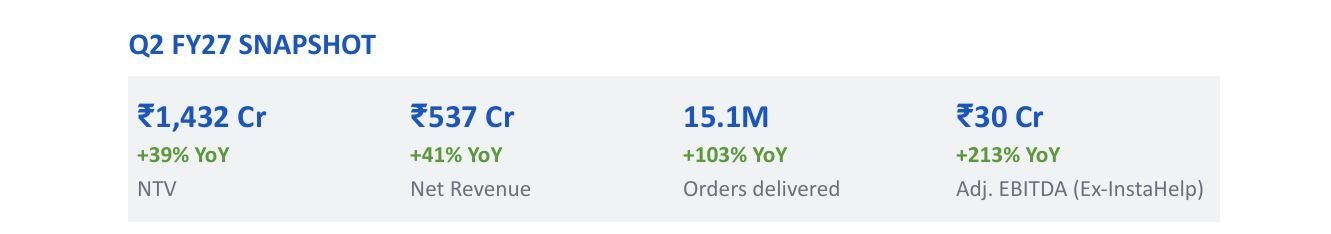
On a consolidated basis, Net Transaction Value (NTV) grew 39% YoY to ₹1,432 Cr. and Revenue from operations grew 41% YoY to ₹537 Cr. Orders delivered reached 15.1 million, up 103% YoY, and annual transacting users reached nearly 10 million, up 35% YoY.
Adjusted EBITDA for the quarter was ₹(144) Cr., reflecting a deliberate ₹(174) Cr. investment in InstaHelp.
Excluding InstaHelp, Adjusted EBITDA was ₹30 Cr., up 213% YoY, and ₹119 Cr. over the past three quarters, up 175% YoY.
The Board has also approved a fresh capital raise of up to ₹2,500 Cr., subject to shareholder approval. The Company closed the quarter with ₹1,901 Cr. in cash and treasury investments.
Growth has stepped up structurally, and every business has a long runway. Consolidated NTV has grown ~40% YoY for three straight quarters, well ahead of the pre-listing trend, driven by accelerating new user acquisition (up 46% YoY over this period), compounding repeat behaviour and densification that is making services faster, cheaper and better. Penetration in the largest categories in the Top 8 cities remains below 10%, Tier 2 cities are growing ~37% YoY and emerging as a second growth engine, International grew 66% YoY and is similar to India in its penetration journey, and Native is building toward a strong festive Q3.
- Growth is driving operating leverage: the core is profitable with expanding margins, even as the Company invests aggressively in InstaHelp by choice. Adjusted EBITDA (Ex InstaHelp) grew 213% YoY to ₹30 Cr., several times the pace of NTV growth. India Consumer Services margin improved 110 bps YoY to 3.5%, International 190 bps to 2.0%, and Native’s loss margin narrowed 220 bps. The consolidated loss of ₹(144) Cr. reflects the ₹(174) Cr. invested in InstaHelp to cement leadership in a winner-takes-most category; unit economics are already improving with density, with loss per order down ~19% QoQ from ₹(346) to ₹(279).
- We are on track to achieve our targets, and are raising capital for strategic flexibility. We closed the quarter with ₹1,901 Cr. in cash and treasury investments, and a core business that generated ₹119 Cr. of Adjusted EBITDA over the past nine months. The business is materially larger than at listing, growth has stepped up, and we now operate three businesses at scale with proven economics. The proposed raise of up to ₹2,500 Cr. is about flexibility: it lets us invest with conviction across each of them, cement leadership in InstaHelp, and pursue inorganic opportunities selectively, without trading off one for another. We remain on track for Adjusted EBITDA breakeven by Q3 FY28 and Adjusted EBITDA of ₹1,000 Cr. by FY31.
Segmental performance highlights for Q2 FY27:
India Consumer Services (Ex InstaHelp)
- NTV: grew 26.3% YoY to ₹963 Cr., achieved against a materially tougher base than in Q1 (Q2 FY26 YoY growth of 19%) and with the festive season this year falling entirely in Q3.
- Adjusted EBITDA: ₹34 Cr., or 3.5% of NTV, compared to 2.4% of NTV in Q2 FY26, a 110 bps improvement YoY.
- Annual transacting users grew 22.4% YoY to ~8.6 million, aided by first-time user growth of ~28% YoY to~0.76 million; NTV per annual transacting user also rose 3.2% YoY.
- Tier 2 cities grew NTV ~37% YoY, continuing to outpace Top 8 city growth.
- Partner earnings: Average net earnings in-hand for active service professionals reached ₹30,708 per month in H1 FY27 (up ~10% from ₹27,950 in H1 FY26), for ~97 hours a month including transit time. The top 20% of professionals by services delivered earned ₹49,178, the top 10% earned ₹53,545, and the top 5% earned ₹56,731 per month.
International
- NTV: Grew 66% YoY to ₹267 Cr. (52% YoY in constant currency); Net Revenue grew 82% YoY to ₹75 Cr. (66% YoY in constant currency). The UAE business has recovered from the disruption caused by the conflict earlier in the year.
- Margins expanded 190 bps YoY to 2.0% of NTV, with both UAE and Singapore delivering another quarter of strong and profitable growth.
- KSA joint venture (Yammak, with SMASCO): NTV grew 153% YoY to ₹93 Cr.; Adjusted EBITDA loss narrowed to ₹(16) Cr. from ₹(20) Cr. a year ago.
Native
- NTV: Grew 35% YoY to ₹132 Cr.; Net Revenue increased 40% YoY to ₹105 Cr.
- Adjusted EBITDA: Loss narrowed to (6.8)% of NTV from (9.0)% a year ago, a 220 bps improvement YoY.
- Recent premium launches — the RO Water Purifier M3 Pro — drove a 4.3% QoQ rise in RO average selling prices, with filter attach rates holding at ~75%.
- With festive season e-commerce sales shifting to Q3 FY27, the Company expects combined Q2+Q3 FY27 NTV
growth of 50–55% YoY. - We received in principle Board approval to explore residential air conditioners as a new category under Native.
InstaHelp - Scale: Fulfilled orders grew 63% QoQ to 6.2 million; NTV grew 34% QoQ to ₹71 Cr.
- Net Order Value declined to ₹114 from ₹138, reflecting competitive intensity and introductory pricing for new
users. - Unit economics: Adjusted EBITDA loss per order improved to ₹(279), from ₹(346) in Q1 FY27, driven by network densification.
- P&L: Adjusted EBITDA loss of ₹(174) Cr. for the quarter, reflecting lower pricing amid competitive intensity, supply built ahead of festive demand in Q3, new user acquisition and expansion into new micro-markets.